Published October 19, 2026
Inflation came in hot. Mortgage rates fell anyway. Here's the weird reason.
Inflation came in hot. Mortgage rates fell anyway. Here's the weird reason.
Last week's money news did not make sense at first glance.
On Wednesday, the government reported that September inflation came in hotter than expected: consumer prices rose 0.6% in a single month and 3.7% over the past year, with gas prices jumping 9.1%. Inflation like that is supposed to push mortgage rates up.
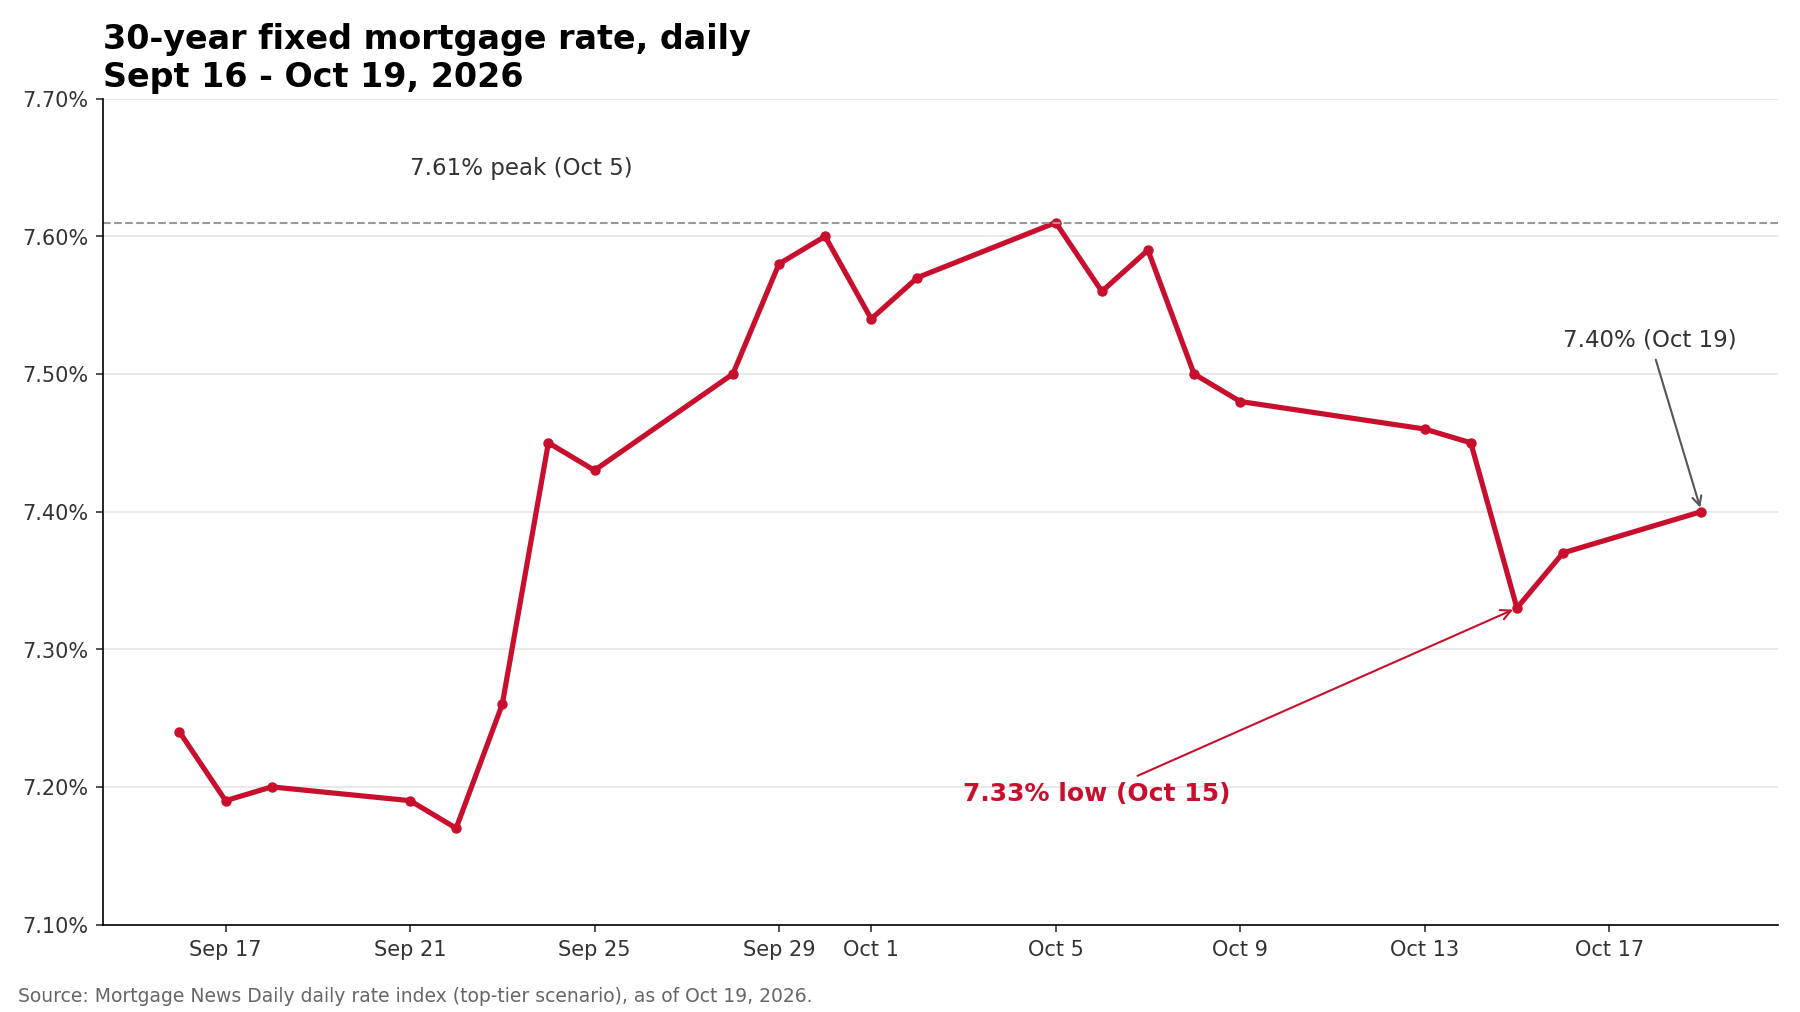
Instead, by Thursday afternoon, the average 30-year fixed mortgage rate had dropped to 7.33% — the lowest in three weeks, according to Mortgage News Daily's daily rate index.
Both things happened. If you're buying or selling in Las Vegas or Henderson, here's what's actually going on, and what to do with it.
The strange reason rates fell
Mortgage rates don't follow the Fed directly, and they don't follow the inflation report directly. They follow the bond market. This week, the bond market got a rush of new buyers for a reason that has nothing to do with housing: a sharp selloff in AI and tech stocks.
When investors get nervous about stocks, they park money in U.S. Treasury bonds. More demand for bonds pushes their yields down, and mortgage rates follow those yields. The 10-year Treasury yield, which had been climbing for weeks and peaked near 5.33%, fell to 5.19% by Wednesday's close and dropped toward 5% during Thursday trading.
Mortgage rates came along for the ride: 7.61% on October 5, 7.33% on October 15. Hot inflation should have stopped that move. The stock market's rough week overruled it.
Two rate numbers, two different stories
You may see two different mortgage rates in the news, and both are real:
- 7.33% — Mortgage News Daily's daily index on Thursday, October 15, down about a quarter point from the prior week's peak. It tracks actual lender rate sheets each weekday, so it catches fast moves.
- 7.40% — Freddie Mac's weekly survey, unchanged from the week before. It's a Thursday-through-Wednesday average, so it moves slowly and hadn't caught up to Thursday's drop. A year ago it was 6.27%.
Neither number is wrong. They measure different things on different schedules. If rates had stayed down, this week's Freddie Mac survey would show it.
The inflation problem hasn't gone away
Before anyone celebrates: September's inflation report was genuinely hot. Prices rose 3.7% over the year, up from 3.4% in August, and energy prices are up more than 20% over the year, largely because of the war with Iran. Wholesale prices jumped 1.3% in September, well above forecasts.
The Federal Reserve raised its benchmark rate in September for the first time in more than three years. As of Thursday, markets were betting there's about a 73% chance the Fed holds steady at its late-October meeting — but another hike is on the table for December. Hot inflation is exactly the kind of thing that pushes mortgage rates back up.
Even Mortgage News Daily's own analyst called this week's rally "act 1 of a very enjoyable show" that "could also be a short story." If the stock market calms down, the bond buying that lowered rate quotes can dry up just as fast. Sure enough, the index has already ticked back up: 7.37% on Friday, October 16 and 7.40% on Monday, October 19. The drop was real. So is how fast it can fade.
What this means in Las Vegas dollars
Put real numbers on it. The median single-family home in the Las Vegas valley was $475,000 in August (Las Vegas Realtors). With 20% down, that's a $380,000 loan:
- At 7.61% (October 5): about $2,686 a month for principal and interest
- At 7.33% (October 15): about $2,613 a month
That's roughly $73 a month — about $19 a month for every $100,000 you borrow. Real money. Not quit-your-job money.
So what should you actually do?
- Under contract? This is a smart week to call your lender about locking. A drop caused by stock-market nerves can reverse quickly.
- House hunting? Use the lower rate to rerun your numbers, not to raise your budget. The monthly payment you were comfortable with last week is still your ceiling.
- Selling? Rates drifting down, even a little, tends to bring some buyers back off the sidelines. One good week doesn't reset the market.
Thinking about buying or selling and wondering what today's rates mean for your specific numbers? Reach out — I'm happy to run them with you.
Sources
- Mortgage News Daily Rate Index (daily lender-rate-sheet index; 7.33% on Oct 15, 7.40% on Oct 19, 2026)
- Mortgage News Daily: Another Big Improvement to Another 3 Week Low (Oct 15, 2026)
- Freddie Mac Primary Mortgage Market Survey (7.40%, week ending Oct 15, 2026)
- U.S. Bureau of Labor Statistics: Consumer Price Index, September 2026
- National Mortgage News: Mortgage rates flat this week, but prepare for uncertainty (Oct 15, 2026)
- FRED: 10-Year Treasury Constant Maturity Rate (DGS10)